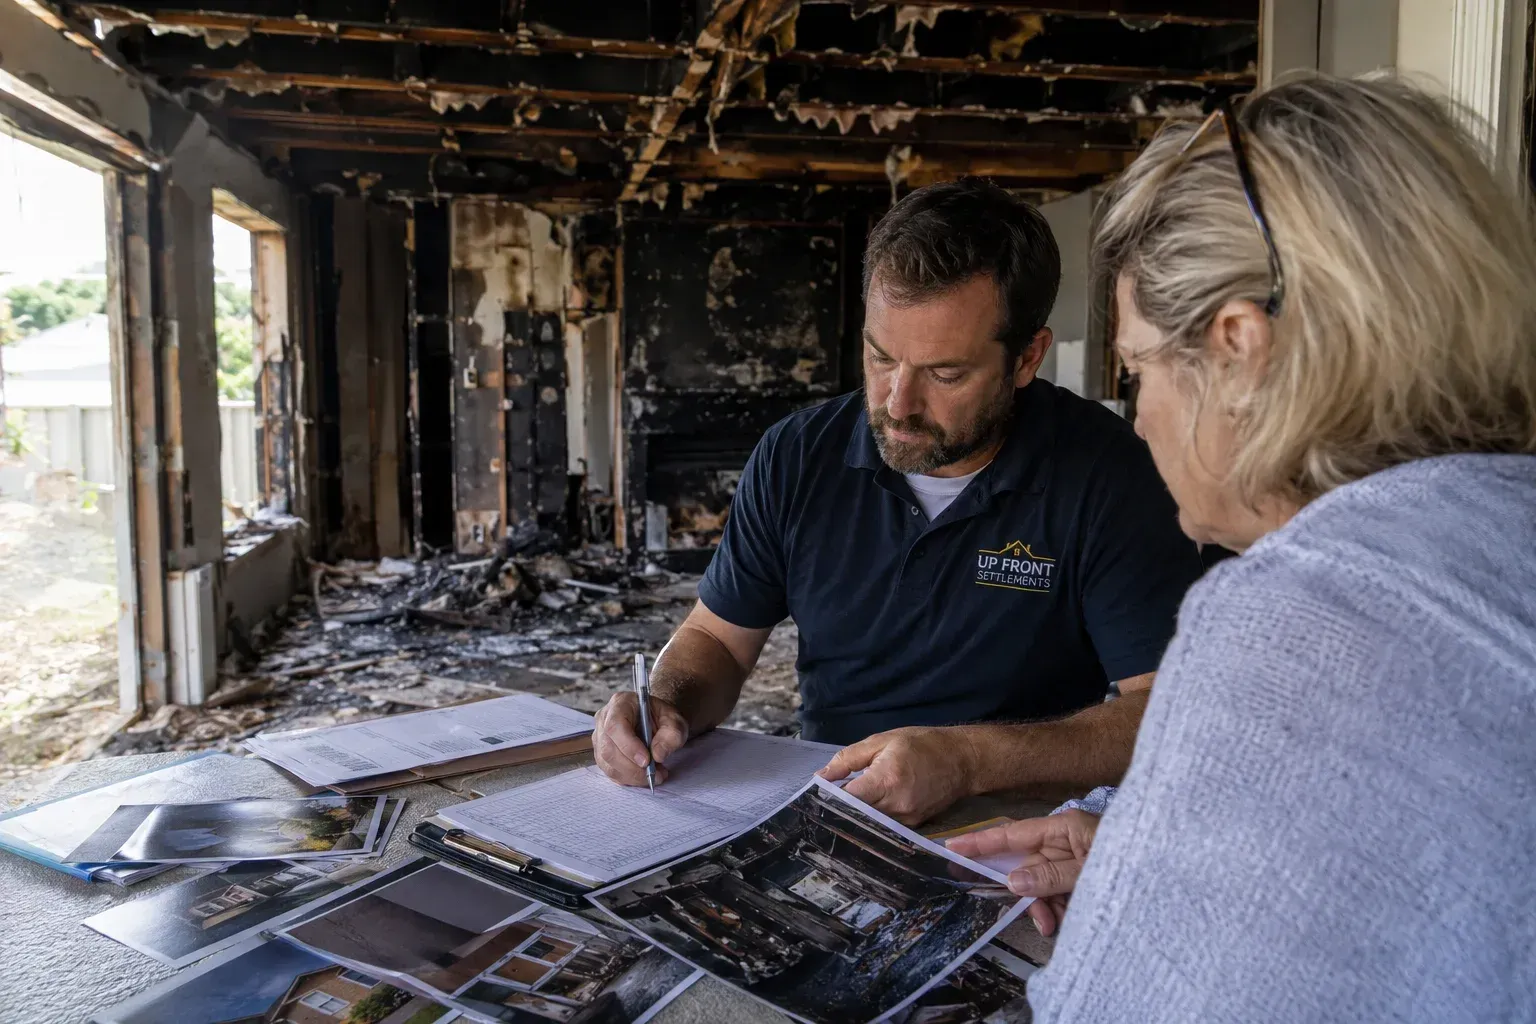
When disaster strikes—whether it’s a fire, storm, burst pipe, or flood—it’s natural to feel overwhelmed. Your first thought is to protect your home and your family. But once the dust settles and it’s time to deal with the insurance claim, many homeowners make small missteps that can turn into big headaches later down the road.
At
Up Front Settlements, we’ve helped Michigan homeowners through just about every kind of property claim you can imagine. And if there’s one thing we’ve learned, it’s this: knowing what not to do can be just as important as knowing what to do. Here are some of the most common mistakes we see—and how you can avoid them.
Calling the Insurance Company Before Talking to a Public Adjuster
It might seem logical to call your insurance company first—but doing that before you’ve spoken with a public adjuster can put you at a disadvantage. The adjuster your insurance company sends is looking out for their bottom line, not yours.
How to avoid it: Reach out to a public adjuster (like our team at Up Front Settlements) before you file your claim. We’ll walk you through the first steps, make sure everything is properly documented, and help you avoid common traps that can cost you in the long run.
Cleaning Up Too Quickly
It’s tempting to start cleaning as soon as possible—no one wants to live surrounded by soaked drywall or fire-damaged furniture. But if you start cleaning before documenting the damage, you could lose out on your claim.
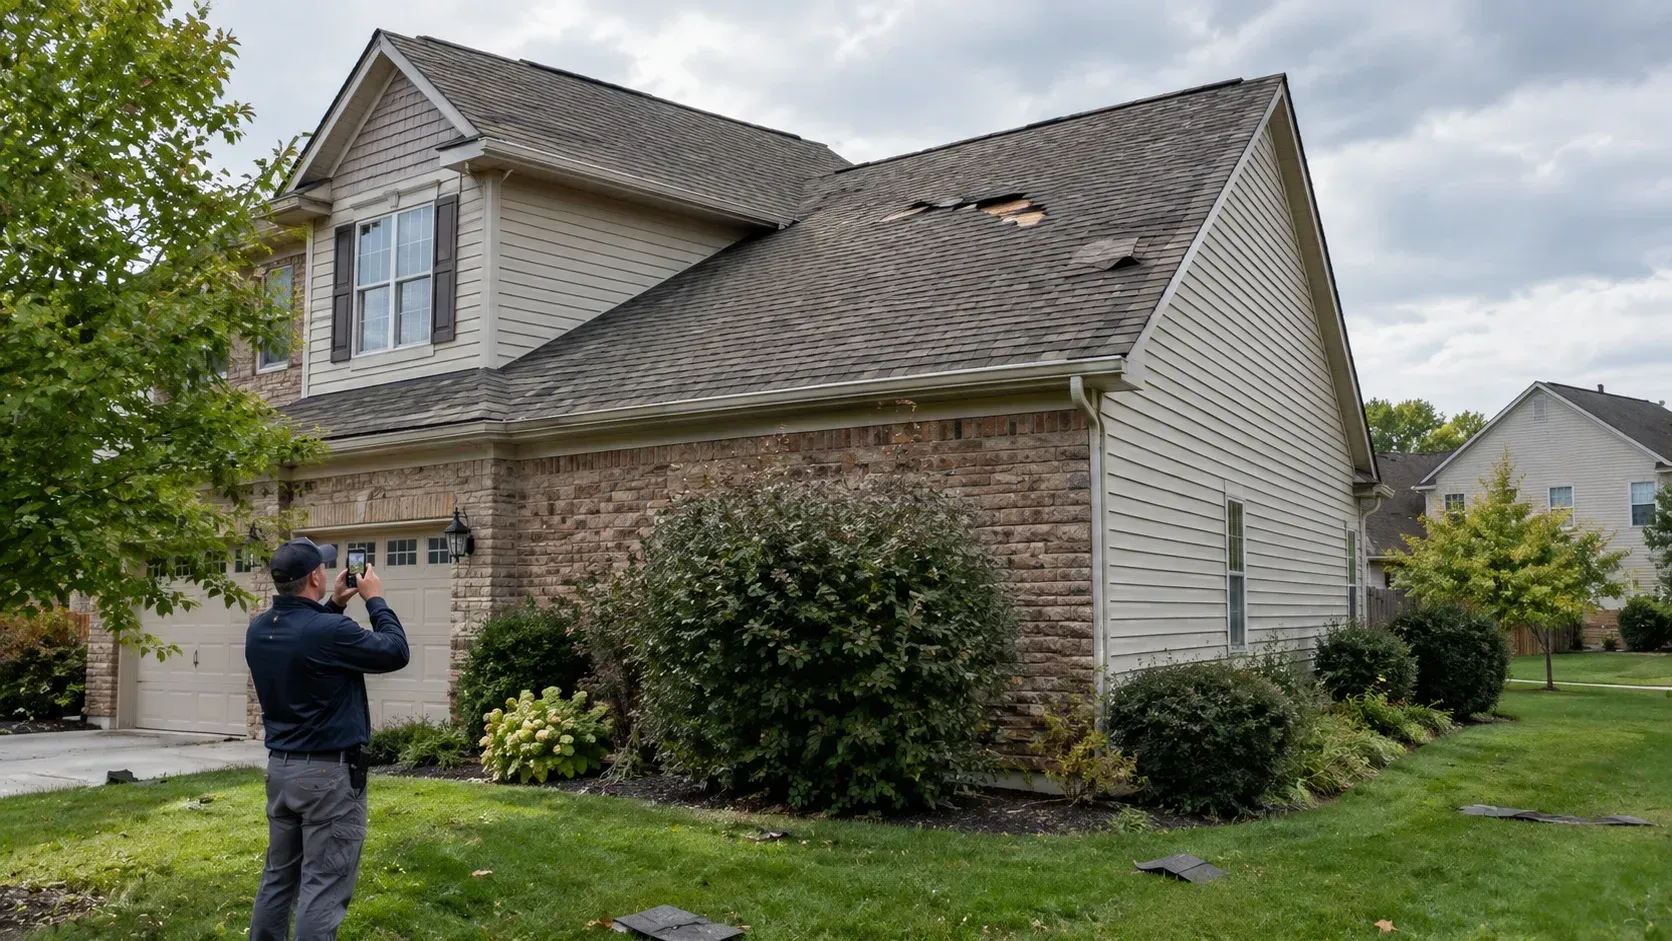
How to avoid it: Pause for a moment. Take plenty of clear photos and videos from every angle. If you need to move anything for safety reasons, make sure it’s photographed first and stored somewhere safe.
Tossing Out Damaged Items Before They’re Documented
We get it—smoke-damaged couches and soaked carpets aren’t exactly things you want hanging around your house. But throwing them out too soon could make it hard to prove your loss.
How to avoid it: Hold onto damaged items until the insurance adjuster (or your public adjuster) has had a chance to inspect them. If space is tight, store them in a garage or covered area after documenting everything.
Assuming the Insurance Company Will Cover Everything
This is one of the biggest misconceptions out there. Most homeowners think, “I’ve paid my premiums, so the insurance company will take care of me.” Unfortunately, that’s not always how it works.
How to avoid it: Don’t leave it up to chance. A public adjuster works for you—not the insurance company—and our job is to make sure you don’t miss out on coverage you’re entitled to.
Not Realizing There’s Hidden Damage
Not all damage is visible. Water can seep behind walls and under floors. Smoke can damage wiring. Wind can shift a roof in subtle ways that don’t show up until months later.
How to avoid it: Let someone experienced inspect the damage thoroughly. We know where to look and what to look for—so nothing gets overlooked in your claim.
Falling Behind on Paperwork and Deadlines
Insurance claims are paperwork-heavy, and deadlines are firm. It’s easy to get caught up in everything else going on and miss a key form or date—especially when your daily life has been turned upside down.
How to avoid it: This is where having help really makes a difference. When you work with Up Front Settlements, we handle the paperwork and follow-up, so nothing slips through the cracks.
Accepting the First Offer Too Quickly
It’s completely understandable to want closure fast, especially when your home is damaged, and your life’s been disrupted. But the first offer from your insurance company is rarely the best one.
How to avoid it: Slow down and let a public adjuster review the offer. We’ll make sure you understand what’s covered, what’s missing, and whether you should negotiate for more (hint: you often should).
Let Us Take the Pressure Off
Filing a property claim isn’t something most homeowners do often—and that’s a good thing. But when you do need to file one, it helps to have someone on your side who’s done it hundreds of times before. At Up Front Settlements, we help homeowners across Michigan avoid the common mistakes that lead to delays, underpayments, or denials.
If your home has been damaged and you’re feeling unsure about what to do next, don’t hesitate to reach out to us here at Up Front Settlements. We will ensure that you receive everything you are owed and avoid your insurance company making things difficult for you!
Contact Up Front Settlements at (248) 841-5674 today or visit us online for more information!